By

October 6, 2026
The Youth Banking Window Is Smaller Than You Think

Welcome to our blog on all things BankingON and our perspective on what's going on in the Credit Union and Banking Industry. If you get a chance, share our posts on social media!
Welcome to our blog on all things BankingON and our perspective on what's going on in the Credit Union and Banking Industry. If you get a chance, share our posts on social media!
Credit unions know they need the next generation.
So they build programs for them. Youth savings accounts.Financial education. Scholarships. Student accounts. All designed to introduceyoung people to financial services.
For years, the formula has been simple:
Open a youth savings account → Teach financial literacy →Graduate the member into checking
But that formula doesn't match how young people experience money today.
Money happens in moments, not milestones
Young people don't think in banking products. They thinkin moments:
Each of these moments is a money decision, and most of them start around middle school.
That's when young people begin making more choices for themselves. They're forming preferences, testing their independence andfiguring out what matters to them. Money is part of that, whether anyone isteaching them or not.
So this is the right time to move from financial education to financial experience. Telling them how to save, spend or budgetisn't enough. They need to actually do it.
Make a decision. See what happens. Try again. Build confidence.
That's how money habits take shape.
Youth banking shouldn’t be a smaller version of the account parents already use. It should be a banking experience designed around how young people live, learn, and make decisions today.
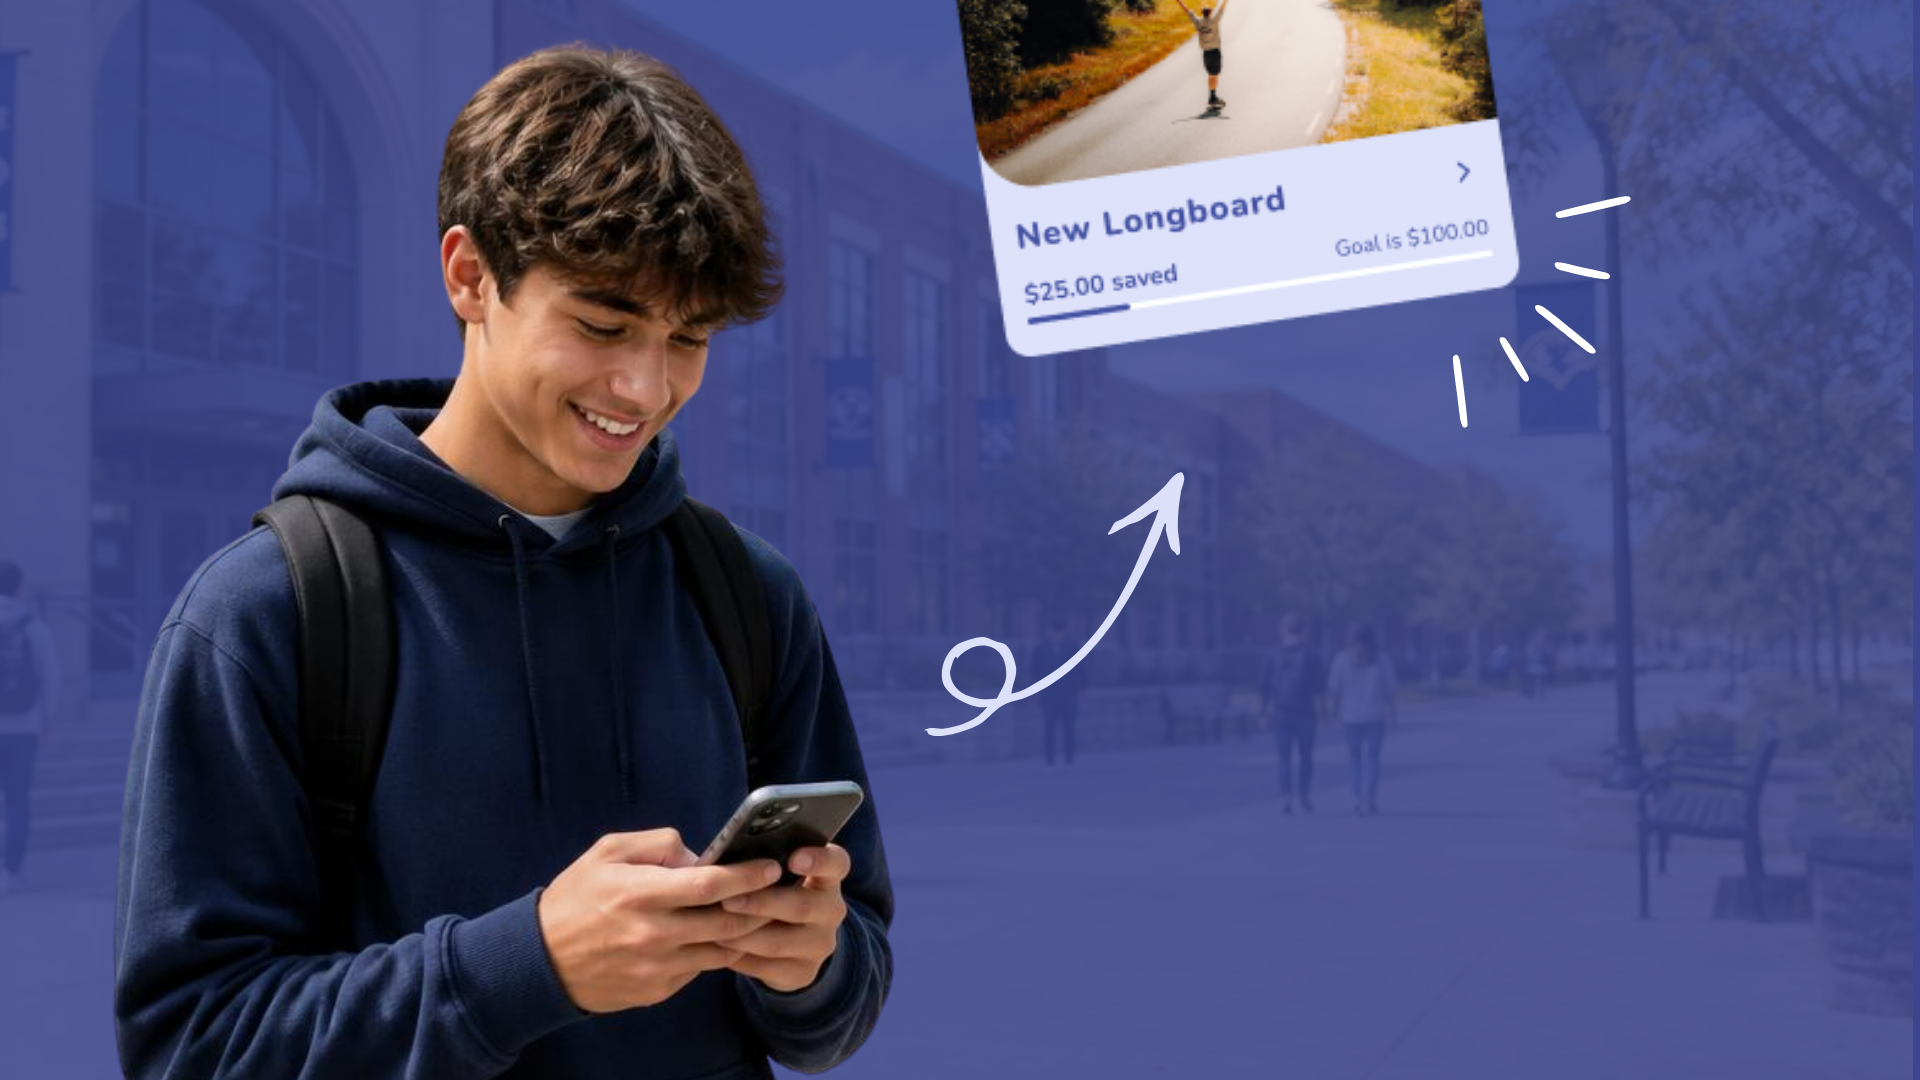
That means more than giving them an account. It means creating an experience that feels simple, intuitive, engaging, and familiar,like the apps they already use, while giving them real opportunities to earn,save, spend, and manage money for themselves.
Parents still have an important role. They should be able to guide, monitor,and set boundaries, while young people get the space to make decisions and learn from them.
A banking experience they actually want to use. Built for them, not just adapted for them.
Credit unions aren't just competing with the bank down the street for young members.
They're competing with whatever becomes that young person's first meaningful financial relationship:
Once one of those becomes familiar, winning that young person over later gets harder. The first experience matters.
Start earlier. The relationship shouldn't begin when a first checking account opens. It should begin when the first money decisions do.
Think beyond the account. Give young people something toactually use: a place to save for what they want, see where their money goes and make their own choices.
Build for the whole family. Parents get visibility and peace of mind. Kids get independence. Both get a reason to stay with theircredit union.
Because if credit unions don't show up during those early years, someone else will. And by the time that young person needs a checkingaccount, a car loan or a mortgage, they'll already have a financial home.
The goal isn't to open a youth account. It's to becomethe place they grow up banking with.
Meet them first. Keep them for life.